Financial decisions become difficult when interest, time, cash flows, and payment schedules interact. The Federal Reserve reported in 2025 that only 63% of U.S. adults could cover a $400 emergency expense entirely with cash or its equivalent. What is a financial calculator in this context? It is a purpose-built tool that converts financial formulas into repeatable keystrokes for loans, savings, investments, bonds, and business analysis.
That statistic shows why transparent scenario testing matters. Comparing a payment, emergency fund, or return can expose tradeoffs before commitment. The tool supports judgment by making assumptions visible, repeatable, and easier to challenge carefully with alternative cases.
What Is a Financial Calculator?
A financial calculator is a handheld device, application, or browser tool designed to solve problems involving money over time. It stores specialized variables and applies formulas for compound interest, annuities, amortization, cash flow, depreciation, and profitability.
The best calculator with financial functions does more than perform arithmetic. It keeps the relationship among periods, interest rate, present value, payment, and future value visible. It helps users compare alternatives consistently when assumptions and entries are correct.
HP introduced the HP-12C in 1981; the HP Virtual Museum calls it the company’s longest-selling calculator. In January 2026, CFA Institute authorized only the Texas Instruments BA II Plus and HP-12C families for its examinations.
Why Is a Financial Calculator Important?
Understanding what is a financial calculator matters because small changes in rates, timing, fees, and compounding can create large differences over long periods. It lets users test scenarios without rebuilding formulas manually.
Benefits include:
- Faster loan and savings calculations
- Consistent treatment of periods and compounding
- Clear comparison of financing or investment alternatives
- Offline use in classes, meetings, and examinations
- Repeatable cash-flow analysis
However, it cannot validate an interest rate, tax assumption, forecast, or investment risk. It computes the model entered by the user.
How Does a Financial Calculator Work?
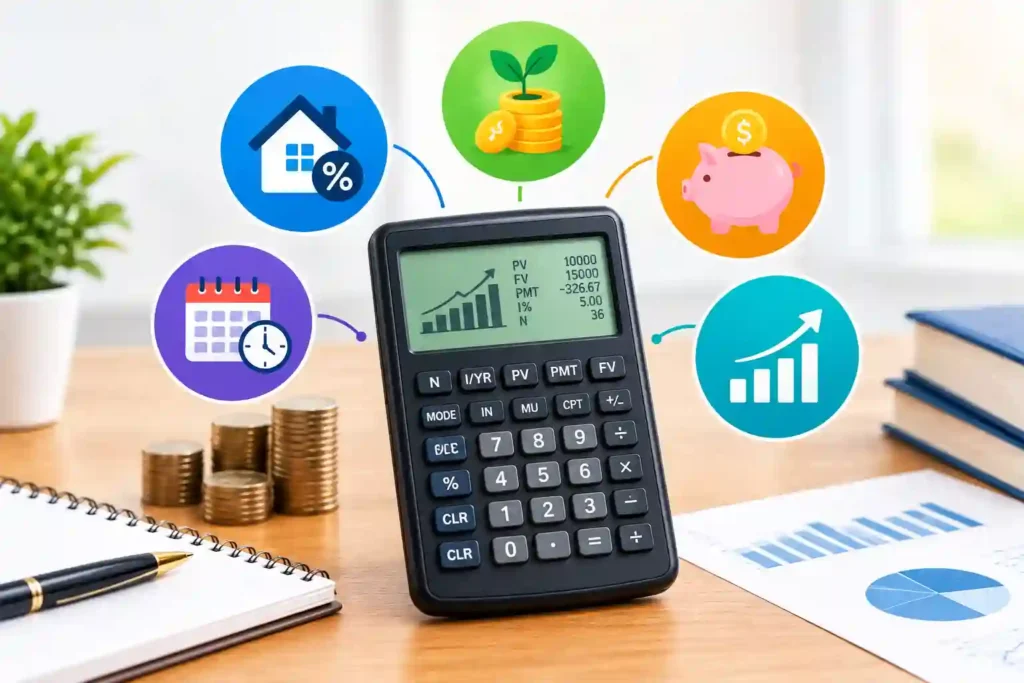
To answer what is a financial calculator technically, start with its time-value-of-money variables:
- N: total periods
- I/Y: interest rate
- PV: present value
- PMT: recurring payment
- FV: future value
The user enters four known variables and asks the calculator to solve for the fifth. Firmware applies the relevant equation. A $100,000 loan may be entered as positive cash received, while repayments are negative outflows. Reversing signs can create errors.
A modern calculator with financial functions may also store payment frequency, compounding frequency, beginning-or-end payment mode, decimals, and date conventions. Treating a monthly rate as annual, or leaving an annuity due in end mode, can distort the answer.
Core Financial Calculator Functions
Texas Instruments’ BA II Plus guide lists worksheets for time value of money, amortization, cash flows, NPV, IRR, depreciation, statistics, rate conversion, dates, margin, and breakeven analysis.
Common capabilities include:
- Loan payments, balances, interest, and amortization
- Future value of regular savings deposits
- NPV and IRR for projected cash flows
- Bond price, yield, and accrued interest on supported models
- Markup, margin, breakeven volume, and depreciation
- Nominal, periodic, and effective-rate conversion
- Settlement dates and days between dates
InfraTech Hub’s Loan, Compound Interest, Percentage, and ROI calculators offer focused alternatives.
How to Use Financial Calculator Controls Correctly
Learning how to use financial calculator controls requires a disciplined sequence:
- Define the question and estimate a reasonable answer.
- Clear earlier worksheets, registers, and modes.
- Set payments and compounding periods.
- Confirm beginning or end payment timing.
- Enter inflows and outflows with consistent signs.
- Store known variables and compute the unknown.
- Check units, timing, magnitude, and assumptions.
Suppose $10,000 earns 6% annually for five years with no additional deposits. Enter N = 5, I/Y = 6, PV = -10000, and PMT = 0; then solve for FV. The result is about $13,382.26; negative PV is invested today, and positive FV is received later.
When learning how to use financial calculator methods, do not copy keystrokes without understanding the timeline. Draw it first when cash flows occur on different dates.
Main Types of Financial Calculators
1. Nonprogrammable Handheld Models
These devices solve standard finance problems through dedicated keys or worksheets.
Pros
- Portable, dependable, and usually offline
- Often accepted in professional examinations
- Fast for repeated TVM and cash-flow work
Cons
- Small displays and model-specific keystrokes
- Limited explanations on screen
- Manual entry can cause errors
2. RPN and Programmable Models
RPN uses stack-based entry; programmable models save repeated sequences.
Pros
- Efficient after practice
- Useful for repeatable workflows
- Strong legacy support in finance and real estate
Cons
- Steeper learning curve
- Unfamiliar to algebraic-entry users
- Programs need testing and documentation
3. Financial Calculator Applications
A mobile or desktop calculator with financial functions may provide charts, timelines, saved scenarios, and explanations.
Pros
- Convenient and visually clear
- Easy to update and share
- Supports varied scenarios
Cons
- Often prohibited in examinations
- Notifications create distractions
- Privacy and formula transparency vary
4. Browser-Based Financial Tools
Online tools specialize in mortgages, retirement, taxes, and returns.
Pros
- Accessible without hardware
- Useful for quick estimates
- May include charts and schedules
Cons
- Assumptions differ among websites
- Sensitive data may be collected
- Internet access may be required
These types of financial calculators suit different settings: students prioritize exam approval, while households may prefer explained online results.
Financial Calculator vs Scientific Calculator
The financial calculator vs scientific choice depends on the problem. A scientific device handles powers, logarithms, trigonometry, and statistics. A financial model organizes cash flows, payments, interest conventions, and valuation variables.
Financial Calculator Pros
- Dedicated TVM, NPV, IRR, bond, and amortization functions
- Faster scenario testing
- Standard financial notation
Financial calculator Cons
- Less suitable for engineering, graphing, or advanced mathematics
- Hidden mode settings can cause errors
- Specialized keys require practice
Scientific Calculator Pros
- Broader mathematical functions
- Usually simpler and less expensive
- Useful across science and engineering
Scientific Calculator Cons
- Financial formulas require more manual entry
- Cash-flow timing is less visible
- Amortization and bond analysis take more steps
This financial calculator vs scientific comparison clarifies what is a financial calculator designed to do: organize financial relationships, not replace every mathematical tool. Link this cluster to InfraTech Hub’s Scientific Calculator guide and Different Types of Calculators pillar.
Common Financial Calculator Errors
Common mistakes include:
- Mixing annual and monthly rates
- Entering years instead of payment periods
- Forgetting to clear earlier values
- Selecting beginning mode for end-of-period payments
- Giving every cash flow the same sign
- Confusing nominal and effective rates
- Rounding intermediate values too early
- Treating projections as guaranteed outcomes
A calculator verifies arithmetic, not economic reality. High-stakes decisions may require qualified advice and independent data.
How to Choose the Right Model
Before buying, ask what is a financial calculator expected to solve in your workflow. Compare the types of financial calculators using:
- Required functions and course syllabus
- Examination approval
- Algebraic or RPN preference
- Cash-flow, bond, statistics, and depreciation needs
- Display and keyboard clarity
- Offline reliability and battery availability
- Tutorials and long-term support
- Privacy for online tools
- Price versus frequency of use
Choose the simplest model that performs every required calculation reliably. Extra functions add little value when setup becomes harder to verify.
Conclusion: What Is a Financial Calculator Worth?
The answer to what is a financial calculator is not merely a calculator for money. It is a structured decision tool that translates rates, periods, payments, and cash flows into comparable results. Used carefully, it improves speed and consistency; used carelessly, it makes flawed assumptions look precise.
Explore InfraTech Hub’s Financial Calculator, Loan Calculator, Compound Interest Calculator, and calculator pillar guide, then verify every mode, sign, unit, and assumption before acting.